

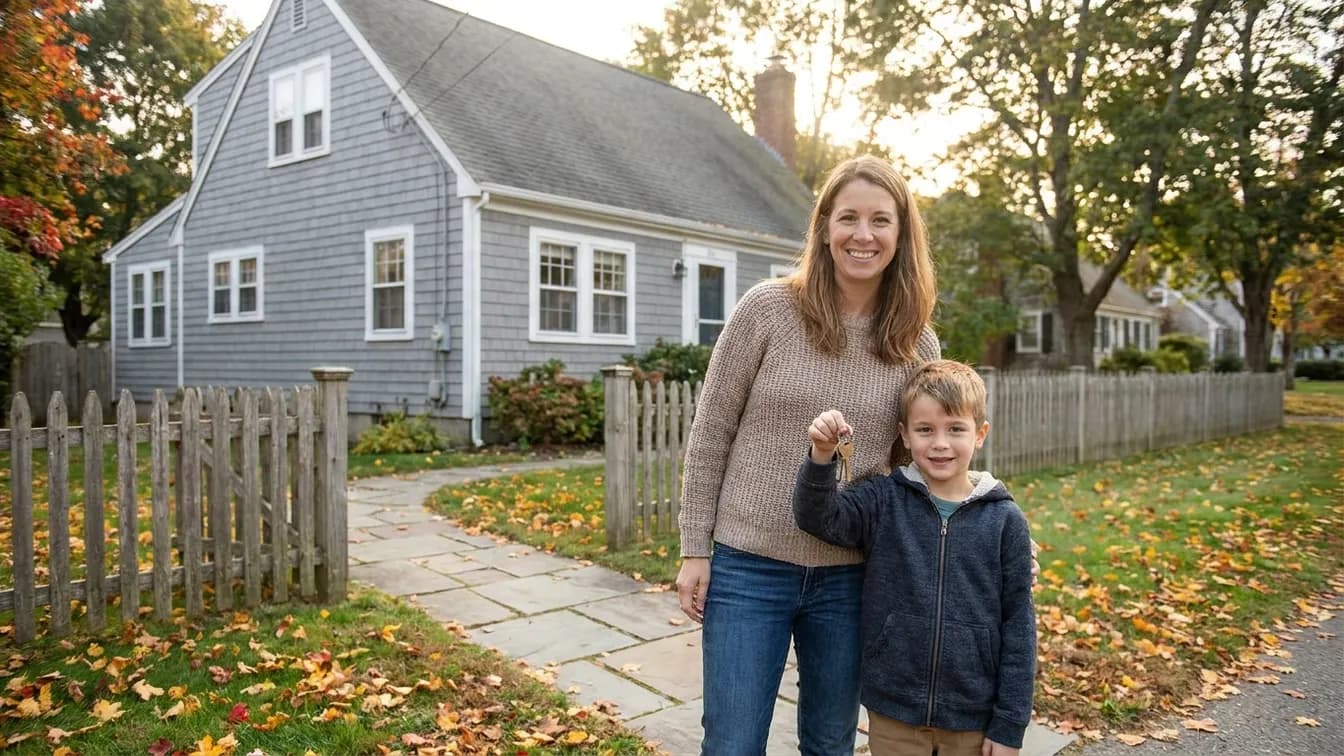
Buying a home on one income while raising children means the mortgage has to fit around rent, groceries, and childcare that already claim every paycheck.
Massachusetts lenders can count child support and alimony toward your income, several loans need only 3% to 3.5% down, and state and city programs can cut the cash you need to close.
Check Your Massachusetts Home Purchase Eligibility
With those rules in hand, you can document your income, compare loans and down payment assistance, and take the next step on a realistic budget.
Is There a Home Loan Just for Single Moms?
No. There is no mortgage or state program in Massachusetts reserved for single mothers, so you use the same loans and assistance as any other buyer, and what matters is how you qualify on one household income.
Several rules work in your favor:
- Fair lending: The federal Equal Credit Opportunity Act bars lenders from discriminating based on sex, marital status, or because part of your income comes from public assistance.
- Support income is your choice: You do not have to disclose alimony, child support, or separate maintenance unless you want the lender to count it toward your mortgage.
- Your kids count: On programs like ONE Mortgage, income limits rise with household size, and children living with you count toward that number.
- First-time buyer again after divorce: ONE Mortgage and the Boston First-Time Homebuyer Program count you as a first-time buyer if you have had no ownership interest in a principal residence in the past three years.
Can Child Support and Alimony Count as Income?
Yes, on both conventional (Fannie Mae) and FHA loans, if you choose to include it and can document it. Counting child support, alimony, or separate maintenance raises your qualifying income and lowers your debt-to-income (DTI) ratio, which is the share of your gross monthly income that goes toward monthly debt payments.
What Conventional Lenders Need
When you ask a lender to count support on a Fannie Mae conventional loan, you need four things:
- Legal paperwork: A final divorce decree, a separation agreement, another written legal agreement or court decree, or a state law requiring the payments. If you are separated without a written agreement setting the payments, proposed or voluntary payments do not count.
- Six months of receipts: Full, regular, on-time payments shown on your last six months of bank statements, cancelled checks, or electronic receipts. Lump-sum equalization payments do not count as steady income.
- Three more years: Payments must be expected to continue for at least three years from your application date, which lenders check against your order and your children's ages.
- Gross-up: Because child support is nontaxable, the lender can "gross up" the support amount when calculating your income, giving each monthly support dollar more qualifying power.
If Fannie Mae's automated underwriting system validates the income, its findings may set different documentation rules.
What FHA Lenders Need
FHA loans also count alimony, child support, and maintenance when backed by a court order or decree, proof of receipt, and at least three years of continuance. Because the exact receipt history depends on how your payments are ordered and documented, your FHA lender will confirm what your file needs.
| Requirement | Conventional (Fannie Mae) | FHA Loan |
|---|---|---|
| Disclosing it | Optional; counted only if you ask the lender to consider it | Optional; disclosed only if you want it counted |
| Paperwork | Divorce decree, separation agreement, legal agreement, or state law mandate | Court order or decree; lender confirms options |
| Receipt history | At least 6 months of full, regular, on-time payments | Proof of receipt required; lender confirms the period |
| Continuance | At least 3 years from the application date | At least 3 years |
| Tax gross-up | Allowed for nontaxable child support | Confirm gross-up calculation with your FHA lender |
If Your Child Is a Teenager
The three-year continuance rule is where teenagers' ages matter.
Under Massachusetts law, a court may order child support past age 18 in two situations: up to under age 21 for a child who lives in a parent's home and is principally dependent on that parent, and from age 21 to under age 23 if that dependence is because the child is enrolled in an undergraduate educational program.
If your court order ends within three years of your application, that support may not pass the continuance test. A loan officer will review the exact terms of your Massachusetts order or separation agreement alongside your children's ages to confirm what can count.
Check Your Massachusetts Home Purchase Eligibility
How Much Do You Need for a Down Payment?
You do not need 20% down. Most single-income buyers compare three standard low-down-payment loans alongside the ONE Mortgage Program, and all three standard loans allow documented gifts from family with a gift letter.
- Fannie Mae Standard 97% LTV: 3% minimum down payment as long as at least one borrower on the loan is a first-time homebuyer.
- Fannie Mae HomeReady: 3% down for first-time or repeat buyers with qualifying income at or below 80% of the Area Median Income (AMI) for the property's location on Fannie Mae's AMI Lookup Tool.
- FHA loan: An FHA loan in Massachusetts requires 3.5% down with a 580+ credit score, or 10% with 500 to 579. It often fits when credit is recovering after a divorce or DTI is tight.
| Loan | Minimum Down | Key Rule | Family Gifts |
|---|---|---|---|
| Fannie Mae 97% LTV | 3% | At least one borrower is a first-time buyer | Yes, with a gift letter |
| Fannie Mae HomeReady | 3% | Qualifying income at or below 80% of AMI for the property location | Yes, with a gift letter |
| FHA Loan | 3.5% (580+ credit) or 10% (500–579 credit) | Primary residence | Yes, per FHA gift rules |
| ONE Mortgage (MHP) | As little as 3% | First-time buyer (3-year rule), income limit by community and household size, assets under $100,000, homebuyer class | Confirm with a participating lender |
State Programs That Lower the Cash You Need
Two statewide agencies, the Massachusetts Housing Partnership (MHP) and MassHousing, offer affordable first mortgages and down payment help through participating lenders. Next Wave Mortgage is not a participating MassHousing or ONE Mortgage lender; our team helps you check eligibility, compare wholesale loan options alongside state programs, and get pre-approved.
ONE Mortgage
Run by MHP, the ONE Mortgage program in Massachusetts requires as little as 3% down and has no private mortgage insurance (PMI), which keeps the monthly payment lower than on standard low-down-payment loans. It also features a low fixed interest rate and additional financial assistance for eligible buyers.
You must be a first-time buyer under the three-year rule and complete an approved homebuyer education class before closing. Income limits vary by community and household size, and households with assets over $100,000 do not qualify. Because income limits change yearly, confirm current figures with a participating lender or MHP at 1-800-752-7131.
MassHousing Down Payment Assistance
Paired with a MassHousing first mortgage, MassHousing down payment assistance offers up to $30,000 in every city and town in Massachusetts for income-eligible first-time buyers of a single-family home, condo, or 2- to 4-family primary residence.
You must complete a homebuyer education course, and a MassHousing-approved lender determines which option and dollar amount you qualify for under current income limits:
- 0% deferred second mortgage: Up to $30,000 with no interest and no monthly payments, repaid only when you sell, refinance, or pay off the first mortgage.
- Amortizing 15-year second loan: Up to $25,000 repaid monthly over 15 years alongside your first mortgage.
A Safety Net If You Lose Your Job
The biggest worry on one income is losing your job with no backup paycheck. MassHousing addresses that with MI Plus, a payment protection benefit included at no extra cost on loans insured through the MassHousing Mortgage Insurance Fund, which covers MassHousing loans with MassHousing mortgage insurance and partner community bank loans insured through the Fund.
If you lose your job, MI Plus can cover your principal and interest up to $4,000 per month for up to six months—up to $24,000 in total—on loans approved for mortgage insurance on or after July 1, 2024.
Loans approved before that date receive up to $2,000 per month, and since 2004 more than 1,500 borrowers have received over $7.8 million in MI Plus benefits.
City Programs Can Add More
Many Massachusetts cities and towns run their own grants and deferred loans to help cover down payment and closing costs, which you can compare in our guide to Massachusetts first-time homebuyer grants and programs.
Under rules updated October 16, 2026, Boston offers up to 3% of the price plus eligible closing costs (up to $50,000) under 100% of AMI, or up to 2% plus closing costs (up to $35,000) between 101% and 135% of AMI. Household assets must be under $100,000.
Boston residents get a grant while non-residents get a 0% deferred loan (effective September 15, 2026), for 1- to 3-family homes and condos with a CHAPA-approved Homebuying 101 class; see our Boston first-time homebuyer programs guide for full details.
Other Massachusetts cities run their own homebuyer programs with local residency, property, and income rules, so check with the local housing office or a participating lender where you plan to buy.
Making One Income Go Further
How you structure the purchase matters as much as the loan you pick.
- Budget for childcare yourself: Lenders calculate DTI from credit-report debts plus the new housing payment, and childcare does not show up on a credit report. Test your real monthly numbers in our home affordability calculator.
- Consider a two- or three-family home: Live in one unit and lenders can count part of the rent from the others, subject to program rules. MassHousing DPA allows 1 to 4 units and Boston allows 1 to 3; see our multifamily mortgage Massachusetts guide.
- Take the homebuyer class early: ONE Mortgage, MassHousing DPA, and Boston's program all require a course before closing. CHAPA lists approved Homebuying 101 classes statewide, and taking one early shows which subsidies fit your household.
Check Your Massachusetts Home Purchase Eligibility
Your Step-by-Step Plan
- Decide whether to count support: Check if your job income qualifies alone; if you want support counted on a conventional loan, gather your decree or agreement, six months of payment receipts, and confirm three more years of payments.
- Check credit and savings: See how your credit score lines up with 3% down conventional or 3.5% down FHA (580+ credit). If family will help with a gift, wait for your loan officer's gift letter instructions before moving the money.
- Compare assistance: Line up your household size and income against ONE Mortgage, MassHousing DPA, and any city program. Remember that ONE Mortgage and Boston's program cap household assets at $100,000.
- Take a CHAPA-approved Homebuying 101 class: Finishing the certificate early keeps it from delaying your closing if you use state or city assistance.
- Get pre-approved: An eligibility check with our team takes no hard credit pull, and pre-approval takes 1 to 3 business days once documents are in. We compare wholesale lenders alongside state and city programs.
- Shop with a firm monthly budget: Look for a single-family home, condo, or 2- to 3-family property that leaves room for childcare and utilities; typical purchase closings take 30 to 45 days from an accepted offer.
You do not need a special single-mom grant or two paychecks to buy a home in Massachusetts. Schedule a free 15-minute call with a loan officer or start online with no hard credit pull to see where you stand today.
Ready to Get Started?
Check your eligibility in under 2 minutes. No credit pull, no obligation.
Get our Massachusetts updates in your Google feed
Add Make Massachusetts Your Home as a preferred source to see our rate, grant, and program updates more often in Google Search.